How to Choose the Right Rental Property for Your Investment Goals
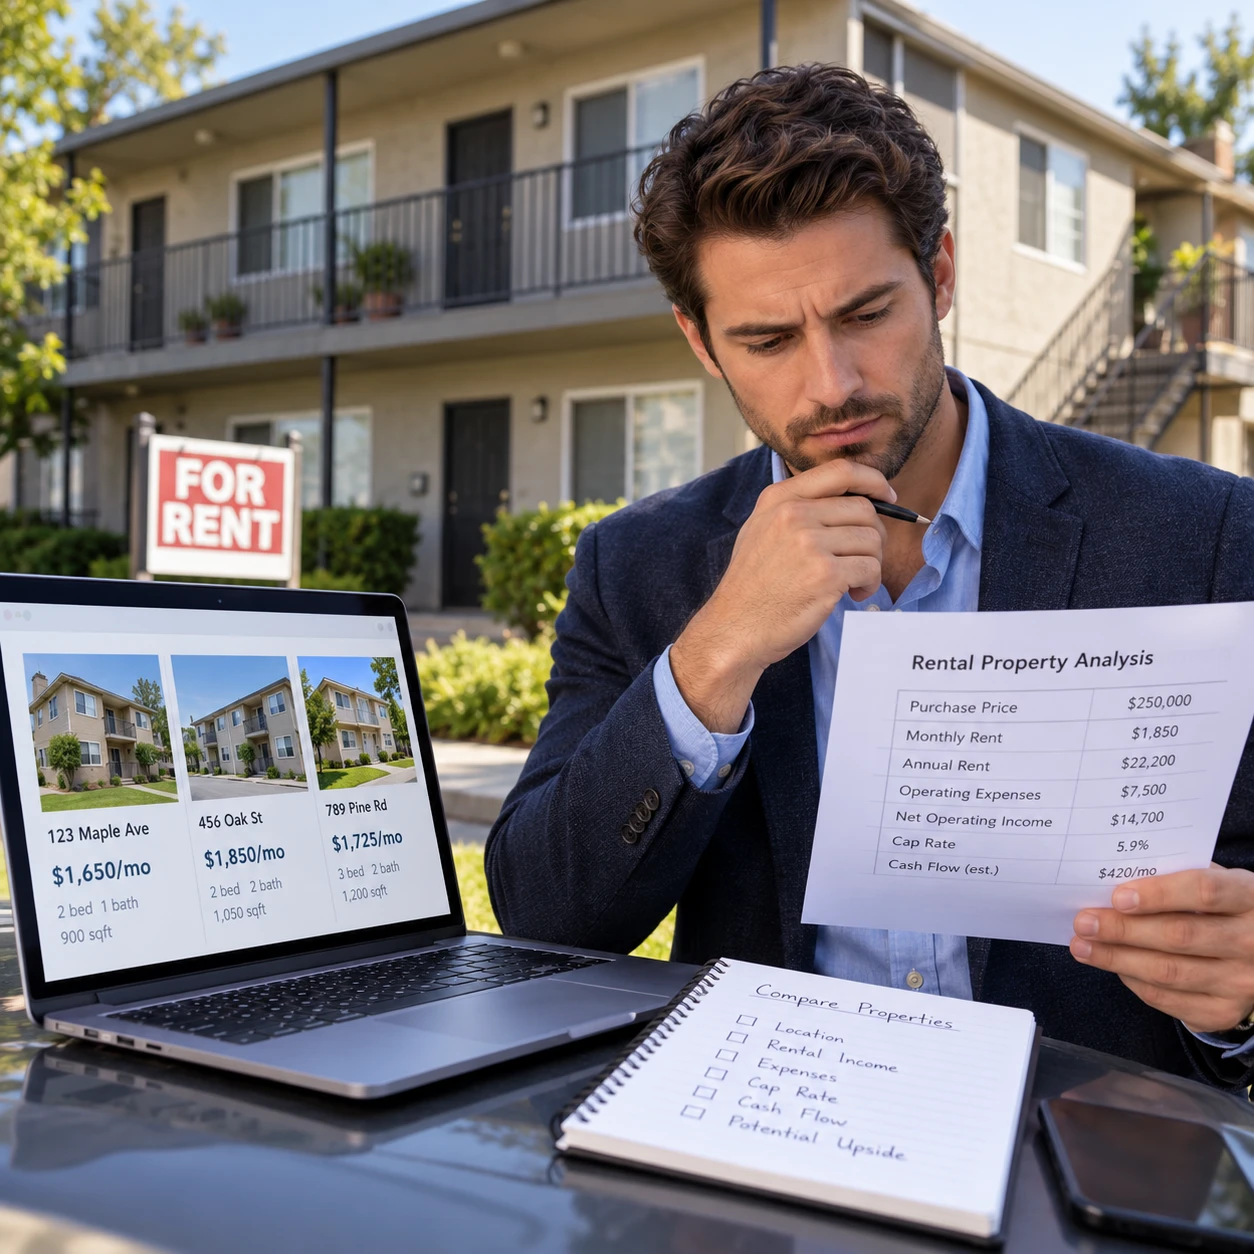
Choosing a rental property starts with deciding what you want the investment to do. A home that produces steady monthly income may differ from one chosen for long-term appreciation, so compare each candidate against your goals, budget, time horizon, and willingness to manage tenants.
Use a consistent process: define your priorities, check local renter demand, test the numbers with realistic costs, and inspect the property before committing. No property guarantees a return, but careful screening can help you avoid investments that do not fit your plan.
Define your investment goals and time horizon
Define your investment goals before reviewing properties: decide whether you prioritize monthly cash flow, long-term appreciation, or a balance of both. Your time horizon and tolerance for risk shape which trade-offs make sense.
If you need regular income, focus on properties where expected rent can cover financing and operating expenses with room for vacancy and repairs. If you can hold the property for many years, you may place more weight on location fundamentals and potential appreciation, while accepting that future values are uncertain. A balanced strategy seeks both, though it may require compromise on purchase price, property type, or initial yield.
Write down your requirements before searching. Include your available down payment, maximum monthly contribution if the property runs at a loss, desired holding period, and how much time you can give to ownership. These boundaries turn broad goals into filters you can apply to listings.
- Income first: Test whether rent can support expenses and debt payments.
- Growth first: Consider the area's long-term appeal, without treating appreciation as guaranteed.
- Balanced: Compare both current rental yield and the reasons tenants may keep choosing the location.
Choose a property type and rental strategy
The right property type and rental strategy depend on your budget, experience, local rules, and capacity for hands-on work. Compare long-term rentals with short-term rentals on both income potential and operating demands.
Single-family homes can appeal to renters seeking more space and may be straightforward to understand, but one vacancy can remove all rental income. Multifamily properties spread income across several units, though they can bring more maintenance, tenant coordination, and upfront cost. Condos may offer shared amenities and exterior maintenance through an association, but fees and rules can affect your returns and rental options.
Long-term rentals often offer more predictable occupancy and fewer turnovers. Short-term rentals may bring higher nightly rates in suitable markets, but revenue can fluctuate with seasonality, cleaning, furnishing, licensing, and platform costs. A higher advertised rate does not automatically mean stronger net returns.
For a first investment, choose an arrangement you can operate responsibly. A simpler long-term rental may be a better fit than a complex short-term setup if you lack time to handle frequent guest communication or local compliance. Confirm that the intended use is permitted before making an offer.
Evaluate location and tenant demand
Evaluate location by identifying who is likely to rent the property and why they would choose that area. Employment access, transport, amenities, and competing rentals help reveal whether tenant demand is practical rather than assumed.
Start with the likely renter base. A property near major employers, colleges, hospitals, transit, or everyday services may suit particular groups, but proximity alone cannot prove demand. Look at comparable rentals in the same area, their asking rents, condition, and how long they appear to remain available. Ask local property managers or agents about tenant preferences and seasonal patterns, then verify claims independently where possible.
Consider the full renter experience: commute, parking, schools where relevant, grocery access, noise, and safety. Also check whether new housing supply or a major employer change could affect competition. A location can be attractive overall yet still perform poorly for a specific unit if the rent is out of step with local incomes or the property lacks features tenants expect.
Separate established facts from forecasts. Current comparable rents and vacancy observations can inform an estimate; planned infrastructure or future development is less certain. Build your decision around evidence you can check today.
Assess the numbers before you buy
Assess a rental property's numbers by estimating its full purchase cost, realistic rent, financing, operating expenses, and likely cash flow. Use conservative assumptions so the investment still makes sense if income is lower or costs are higher than expected.
Begin with the purchase price and acquisition costs, including closing fees, inspections, immediate repairs, and any furnishing required by the rental strategy. Then estimate financing costs using actual loan terms, not a generic interest rate. Rent estimates should come from comparable properties with similar location, size, condition, and lease terms.
List recurring operating expenses. These may include property taxes, insurance, association fees, utilities paid by the owner, routine maintenance, repairs, property management, advertising, and vacancy. Keep a separate reserve for larger replacements, such as a roof or heating system, instead of assuming those costs will not arise.
A simple monthly cash-flow estimate is:
Expected rent − vacancy allowance − operating expenses − debt payments = estimated cash flow.
Rental yield compares rental income with property cost, while return on investment (ROI) considers the return relative to the money invested. Definitions and calculations vary, so use the same method when comparing candidates. For a general overview of rental housing considerations, consult the U.S. Department of Housing and Urban Development's rental housing resources; local rules and costs still require local verification.
Run at least one downside scenario: lower rent, a vacant month, or an unexpected repair. If that scenario would strain your finances, adjust the offer, increase reserves, or pass. Strong-looking projected ROI is only useful when its assumptions are credible.
Inspect the property and estimate ongoing work
Inspect the property before purchase and estimate both immediate repairs and ongoing maintenance. A professional property inspection can uncover defects that change the investment's true cost or make the property unsuitable for your rental plan.
Review the roof, foundation, plumbing, electrical system, heating and cooling, windows, drainage, and visible signs of moisture or pests. Ask the inspector to flag issues needing specialist evaluation. An inspection is a snapshot, not a warranty; it cannot predict every future repair or replace checks required by local law.
Translate findings into a written work plan. Separate urgent safety or habitability items from optional improvements, then obtain contractor estimates where needed. A cosmetic upgrade may help a unit compete for tenants, but only if the likely rent or occupancy benefit justifies the cost. Avoid spending on features renters in that market do not value.
Also consider the maintenance profile of the building. Older systems, shared spaces, landscaping, and deferred repairs can add recurring demands. Compare the cost and timing of the work with your available cash reserves, not just the property's expected rent.
Weigh management needs and investment risks
Weigh management needs against your available time, experience, and budget. Self-management can reduce fees but requires tenant communication and coordination; hiring a property manager adds cost while shifting some day-to-day work to a professional.
Ask managers about their fees, leasing process, maintenance approval limits, reporting, and experience with the specific property type. Confirm what is included and what costs extra. Self-managing owners should understand local landlord-tenant rules, fair housing obligations, required disclosures, and procedures for handling repairs and deposits.
Plan for risks that can disrupt income or increase costs:
- Vacancy and nonpayment: Use a vacancy allowance and screen applicants lawfully and consistently.
- Unexpected repairs: Keep reserves separate from the down payment and planned renovation budget.
- Regulatory changes: Verify local licensing, inspection, zoning, and rental restrictions before purchase.
- Concentration: Consider whether one property or one tenant market would expose too much of your capital to a single setback.
Property management does not remove investment risk, and self-management is not free simply because there is no management invoice. Include your own time, travel, and coordination effort in the decision.
Use a final property-selection checklist
Use a final property-selection checklist to compare each candidate against your goals, local demand, realistic finances, condition, and management capacity. A property should meet your essential requirements before its projected upside influences the decision.
- Does the property support a defined goal and holding period?
- Is the property type and rental strategy permitted and manageable for you?
- Is tenant demand supported by comparable rentals and local evidence?
- Do rent estimates reflect the unit's actual condition and competition?
- Have you included financing, vacancy, operating expenses, repairs, and reserves?
- Does a downside scenario remain financially manageable?
- Have inspection findings and contractor estimates been reflected in your offer?
- Can you manage the property yourself or afford a suitable manager?
Score candidates using the same assumptions and note what remains uncertain. If a property only works under optimistic rent, minimal repairs, and uninterrupted occupancy, its numbers are fragile. The right rental property is the one whose risks and workload you understand and whose likely performance fits your investment goals.