How to Calculate Rental Property Cash Flow
Rental property cash flow shows how much money remains after rent and other property income cover expenses. A reliable calculation accounts for vacancy, operating costs, mortgage payments, and a realistic allowance for major repairs. Use a consistent monthly or annual timeframe so you can compare estimates with actual results.
What rental property cash flow means
Rental property cash flow is the money left from property income after the expenses you choose to include are paid. It can be calculated monthly or annually, but the period must be consistent across every income and cost.
For a practical owner-level estimate, cash flow generally includes operating expenses, debt payments, and reserves for irregular costs such as capital expenditures. A positive result means the property generated more cash than it required during that period; a negative result means you had to contribute funds.
Cash flow is different from revenue, taxable income, and total investment return. It also depends on the calculation’s scope: an estimate before mortgage payments answers a different question from one that includes them. State clearly whether your figure includes financing and reserves, especially when comparing properties.
The rental property cash flow formula
The basic rental property cash flow formula is: Cash flow = effective rental income − operating expenses − mortgage payments − capital expenditure reserves. Use monthly figures for monthly cash flow or annual figures for annual cash flow.
Effective rental income is the rent and other recurring property income you expect to collect after accounting for vacancy and collection losses. Net operating income (NOI) is generally effective income minus operating expenses, before mortgage payments and income taxes.
This gives a useful two-part calculation:
- NOI = effective rental income − operating expenses
- Cash flow after financing and reserves = NOI − mortgage payments − CapEx reserves
Capital expenditures, or CapEx, are larger or less frequent costs that extend a property’s useful life or replace major components, such as a roof or heating system. Setting aside a monthly reserve does not mean the cash has already been spent; it makes the estimate more realistic by recognizing future needs.
Which income and expenses to include
Include rental income you reasonably expect to collect, then subtract vacancy, operating expenses, mortgage payments, and a reserve for major repairs. Keep each category separate so you can see what is driving the result.
Income may include monthly rent and recurring charges you collect, such as parking or laundry fees. Avoid counting a one-time security deposit as income when it may need to be returned. If rent is uncertain, use a supportable estimate rather than assuming every month will be fully occupied and paid.
Vacancy allowance represents rent lost when a unit is empty or a tenant does not pay. Estimate it using the property’s history or local market conditions. A zero-vacancy assumption can make a projection look stronger than the cash you are likely to receive.
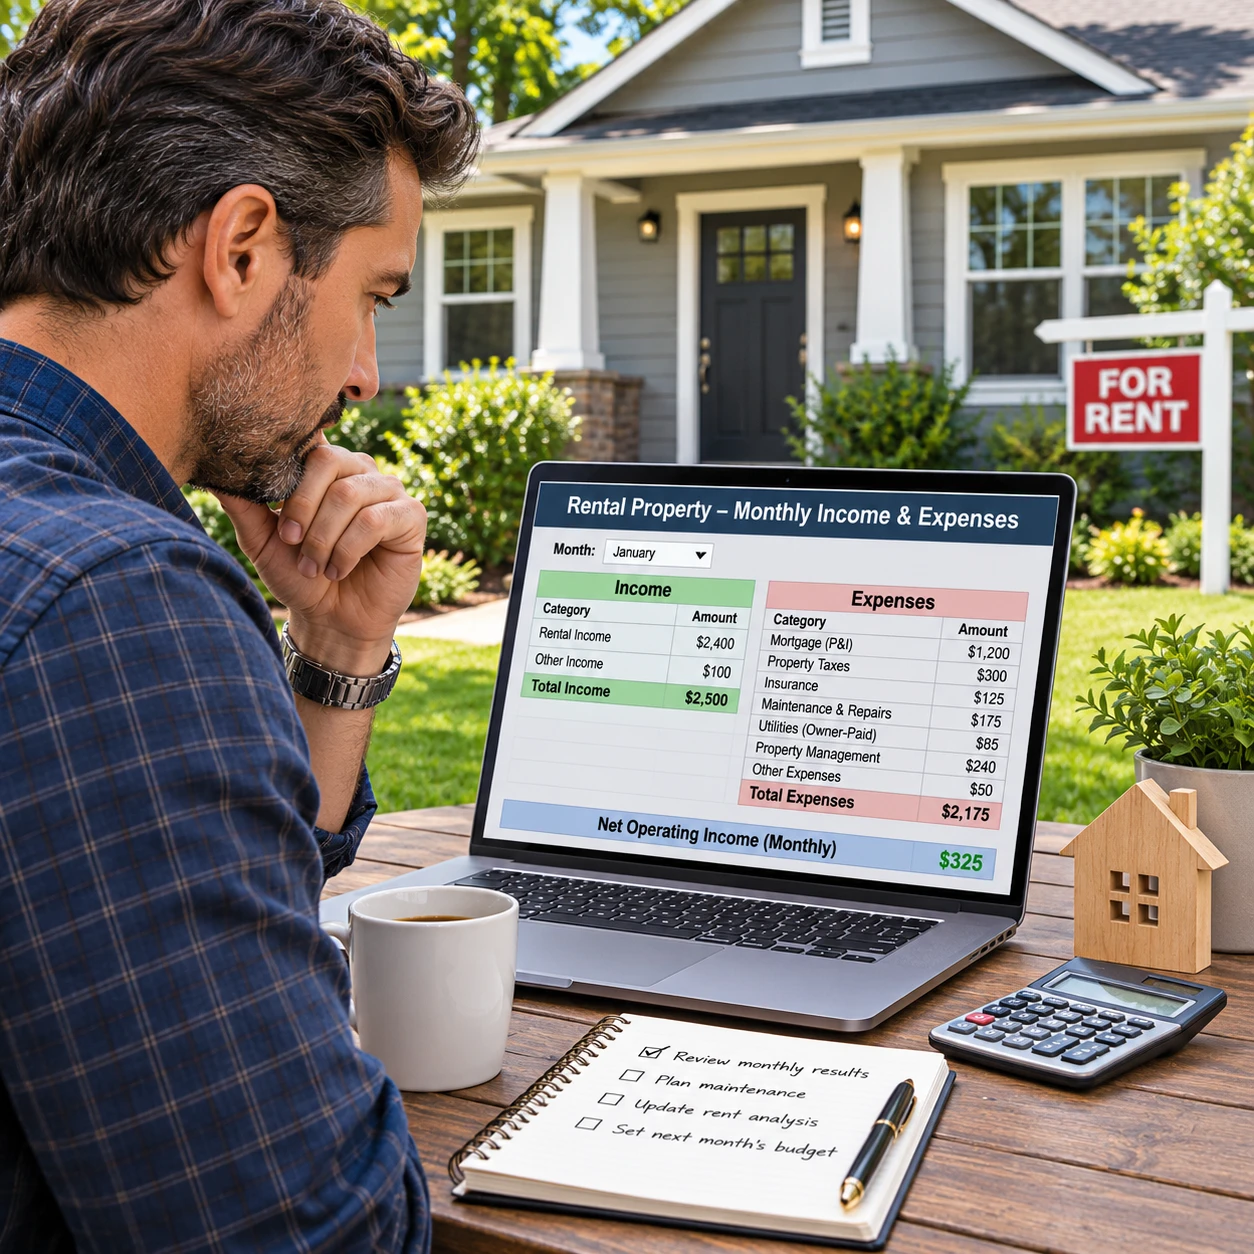
Operating expenses commonly include property taxes, insurance, routine maintenance, repairs, owner-paid utilities, property management, advertising, and association fees. Include recurring costs even if they are billed annually; divide them by 12 for a monthly estimate.
Then account for the mortgage payment if you want cash flow after financing. Use the actual required payment, including principal and interest, and include escrowed taxes or insurance only once. Finally, budget for irregular CapEx, such as appliance replacement or exterior work. The appropriate reserve varies by property age, condition, and local costs, so inspect the property and use a property-specific estimate rather than a universal percentage.
Step-by-step calculation with an example
To calculate rental property cash flow, estimate collectible income, subtract operating expenses to find NOI, then subtract the mortgage payment and CapEx reserve. The following hypothetical example uses monthly figures and assumes expenses are paid by the owner.
- Start with scheduled income: Monthly rent is $2,000, with $100 in recurring parking income, for total potential income of $2,100.
- Subtract vacancy: Allow $105 per month for vacancy and collection loss. Effective rental income is $1,995.
- Subtract operating expenses: Budget $400 for property taxes, $125 for insurance, $150 for routine maintenance, $100 for management, and $70 for owner-paid utilities. Total operating expenses are $845.
- Calculate NOI: $1,995 − $845 = $1,150 per month.
- Subtract financing and reserves: With a $850 mortgage payment and a $150 monthly CapEx reserve, cash flow is $1,150 − $850 − $150 = $150 per month.
Annual cash flow on these assumptions is $150 × 12, or $1,800 per year. That result is an estimate, not a promise: a longer vacancy, an unexpected repair, or a change in insurance costs could reduce it. If you calculate annual cash flow from annual totals, make sure you use the same vacancy and expense assumptions as in the monthly version.
Common calculation mistakes
The most common cash flow calculation mistakes are leaving out expenses, treating NOI as cash flow after financing, and ignoring irregular costs. Each can make a property appear more profitable than its actual cash position suggests.
- Omitting routine costs: New investors may count rent and the mortgage but forget taxes, insurance, management, utilities, or maintenance. List expenses from bills, leases, and property records, and check whether any costs are included in escrow or paid by the tenant.
- Confusing NOI with cash flow: NOI is calculated before mortgage payments. Calling NOI the property’s cash flow after financing overstates the cash available to an owner with a loan. Show NOI and post-debt cash flow as separate figures.
- Ignoring vacancy and collection loss: Assuming full rent every month overlooks turnover and missed payments. Use a realistic allowance based on the property and market, then update it when actual occupancy data changes.
- Skipping irregular costs: A roof, water heater, or appliance replacement may not appear in a typical month. Track CapEx separately from routine repairs and include a sensible reserve in projections. Otherwise, a positive monthly result may not reflect the property’s longer-term cash needs.
How to interpret the result
Positive rental property cash flow means estimated income exceeds the expenses included in your calculation; negative cash flow means the property needs additional funds for that period. Neither result alone proves whether an investment is good or bad.
A positive figure can provide a buffer for operating needs, but its meaning depends on the assumptions and the cash invested. A negative figure may reflect a deliberate financing or improvement strategy, yet it still requires an affordable plan to cover the shortfall. There is no universal monthly amount that counts as “good” cash flow across properties, markets, and financing arrangements.
Cash flow also differs from cash-on-cash return. Cash-on-cash return compares annual pre-tax cash flow with the cash invested, usually expressed as a percentage. For example, $1,800 in annual cash flow on $30,000 invested equals 6%, provided both figures use the same investment scope. This measure does not capture every element of total return, such as changes in property value or loan principal reduction.
Recalculate when rent, occupancy, insurance, taxes, financing, or maintenance assumptions change, and compare estimates with actual income and expenses at least periodically. Keep a simple record of assumptions beside the result. That makes a cash flow figure useful for decisions rather than a number detached from the property’s real costs.
Frequently asked questions
Should I include the mortgage payment when calculating cash flow?
Yes, include the mortgage payment when you want to know cash remaining after financing. You can also calculate NOI before debt service, but label it separately so it is not mistaken for post-mortgage cash flow.
Is rental property cash flow the same as NOI?
No. NOI is effective rental income minus operating expenses, before mortgage payments. Cash flow after financing typically subtracts debt payments and may also account for a CapEx reserve.
How often should I recalculate cash flow?
Review it at least annually and whenever a major input changes, such as rent, vacancy, taxes, insurance, mortgage terms, or a significant repair. Comparing projected and actual figures helps improve future estimates.
What costs are commonly missed?
Common omissions include vacancy, property management, owner-paid utilities, insurance increases, annual fees, routine maintenance, and major replacements. Check leases, bills, tax records, and the property’s condition before finalizing your estimate.